SEBI PMS · Plain-English guide
Understand SEBI PMS
A simple, structured guide to the SEBI (Portfolio Managers) Regulations, 2026
Go section by section through what a portfolio manager is, the three ways of working, who can invest, how client assets are kept, registration, working with clients, PRIM and the other special routes, and what changes on 1 April 2027. Each section links to the regulation it rests on.
India’s PMS rulebook, from 1 April 2027
In force from 1 April 2027. The SEBI (Portfolio Managers) Regulations, 2026 were notified on 7 October 2026 and replace the 2020 Regulations from 1 April 2027. Until then, the 2020 Regulations apply.
01
Section 1
What is a portfolio manager?
A portfolio manager is a company that manages, administers or advises on a client's own portfolio of securities, under a written contract with that client. It must be registered with SEBI.
“portfolio manager” means a body corporate, which pursuant to a contract with a client, advises or directs or undertakes on behalf of the client (whether as a discretionary portfolio manager or otherwise) the management or administration of a portfolio of securities or goods or funds of the client, as the case may be
Regulation 2(1)
Unlike a mutual fund or an AIF, nothing is pooled. Each client's money and securities stay that client's own, held in separate accounts, and the portfolio manager runs them under an individual agreement.
Only a body corporate can be a portfolio manager. It needs a certificate of registration from SEBI before it starts (Chapter II).
In everyday terms: a mutual fund is a shared bus. A portfolio manager is a personal driver for your own car — the car, and everything in it, stays in your name.
02
Section 2
Three ways of working
A portfolio manager can run your portfolio with full discretion, act only on your directions, or simply advise you.
The discretionary portfolio manager shall individually and independently manage the funds of each client according to the needs of the client, in a manner which does not partake character of a Mutual Fund, whereas the non–discretionary portfolio manager shall manage the funds in accordance with the directions of the client.
Regulation 16(1)
Discretionary: the manager decides what to buy and sell for each client, individually. The Regulations say this must not take on the character of a mutual fund.
Non-discretionary: the manager acts on the client's directions. Advisory: the manager only advises; a portfolio manager that provides only advisory services does not need a custodian (Regulation 19).
Think of a discretionary manager as a driver who chooses the route, a non-discretionary manager as a driver who follows your directions, and an adviser as someone who reads the map for you while you drive.
03
Section 3
Who can invest, and how much
The minimum is ₹50 lakh per client for portfolio management, and ₹25 lakh for PRIM. Accredited investors are exempt from the ₹50 lakh minimum.
The portfolio manager shall not accept funds or securities or a combination thereof worth less than fifty lakh rupees per client.
Regulation 16(3)
The ₹50 lakh minimum does not apply to an accredited investor, subject to disclosures in the Disclosure Document and the agreed terms (Regulation 16(4)). A renewal of the portfolio at the end of its initial period counts as a fresh investment (Regulation 16(6)).
A large value accredited investor is an accredited investor whose agreement with the portfolio manager is for at least ₹10 crore (Regulation 2). For them, the Third Schedule agreement contents do not apply (Regulation 15(1)(b)), and up to 100% of their assets may go into unlisted securities, with disclosures (Regulation 17).
For PRIM, the minimum is ₹25 lakh per client (Regulation 33(1)).
Example: a client with ₹40 lakh cannot open a regular PMS account, unless they are an accredited investor. The same ₹40 lakh is enough for PRIM.
04
Section 4
How the money and securities are kept
Each client's securities are kept in separate accounts, client money sits in a separate bank account, and a custodian holds the securities.
The portfolio manager shall segregate each client’s holding in securities in separate accounts. (9) The portfolio manager shall keep the funds of all clients in a separate account to be maintained by it in a Scheduled Commercial Bank.
Regulation 16(8), (9)
Every portfolio manager, other than one that only gives advice, must appoint a custodian for the securities it manages (Regulation 19). The manager acts as a fiduciary for the client's funds (Regulation 16(7)).
What the manager cannot do: borrow funds or securities on a client's behalf, lend clients' securities to third persons except as the Regulations allow (Regulation 16(12), (13)), or use client funds for bill discounting, badla financing or lending to corporate or non-corporate bodies (Regulation 17(2)).
The client's assets never mix with the manager's own or with other clients'. If the manager ran into trouble, the client's holdings are still identifiable as the client's.
05
Section 5
Getting registered
An applicant needs the right infrastructure and people, net worth of at least ₹5 crore, and must pay SEBI's fees.
The applicant shall maintain minimum net worth requirement of at least five crore rupees.
Regulation 4(a)(iv)(a)
At least 10% of that minimum net worth must be in unencumbered liquid assets, such as cash, bank deposits with scheduled commercial banks, money market instruments and government securities (Regulation 4(a)(iv)(c)). The applicant needs a principal officer, a compliance officer and at least one more employee, with the qualifications and experience the Regulations set (Regulation 4).
Fees (First Schedule): ₹1 lakh to apply, ₹10 lakh to register — paid within 30 calendar days of SEBI's intimation (Regulation 3(6)) — and ₹5 lakh for every later block of three years, paid within three months before the block ends (Regulation 7(1)). Once registered, business must start within three years (Regulation 6(7)).
Example: a company with ₹6 crore net worth but only ₹30 lakh in liquid assets meets the net worth figure but not the liquid-asset rule, which needs ₹50 lakh.
06
Section 6
Working with clients
Before taking a client: a Disclosure Document, then a written agreement. After that: regular reports, audits and quick handling of complaints.
Prior to entering into an agreement with client as referred in sub–regulation (1), the portfolio manager shall provide to the client a Disclosure Document in digital format along with a disclosure document certificate in the format as may be specified by the Board from time to time.
Regulation 15(2)(a)
The written agreement sets out the relationship and must contain the details in the Third Schedule (Regulation 15(1)). Investing in securities of related parties or associates needs the client's prior consent (Regulation 15(1)(c)). The Disclosure Document is certified by an independent chartered accountant, updated every year within six months of the year end, and filed with SEBI (Regulation 15(2)).
Each client gets a report at least every three months, and whenever they ask (Regulation 24(1)). Client portfolio accounts are audited every year by an independent chartered accountant (Regulation 23(5)). Grievances must be redressed within twenty-one calendar days (Regulation 16(14)).
Example: a complaint received on 10 April 2027 must be redressed by 1 May 2027.
07
Section 7
The special routes
Three chapters cover special kinds of portfolio managers: PRIM for mutual fund units, eligible fund managers, and co-investment portfolio managers.
The portfolio managers shall invest funds of the client only in direct plans of mutual funds in India including index funds, exchange traded funds and specialized investment funds.
Regulation 32 (PRIM)
PRIM — the portfolio management service route for investment in mutual fund units (Chapter VI). A PRIM-only portfolio manager needs net worth of at least ₹2 crore at all times (Regulation 31), and the client minimum is ₹25 lakh (Regulation 33). Existing portfolio managers may offer PRIM under segregated investment approaches (Regulation 30(2)).
Eligible fund managers (Chapter III) act for eligible investment funds as defined in section 9(12) of the Income-tax Act, 2025. Co-investment portfolio managers (Chapter IV) invest alongside the Category I and II AIFs they manage, putting 100% of their AUM into unlisted securities of the same investee companies, on terms no better than the AIF's (Regulation 12).
PRIM is a lighter route: a smaller net worth and a lower client minimum, in exchange for investing only in direct plans of mutual funds.
08
Section 8
What changes on 1 April 2027
The 2026 Regulations replace the 2020 Regulations on 1 April 2027. Registrations carry over, and existing portfolio managers get time to meet some new requirements.
The Securities and Exchange Board of India (Portfolio Managers) Regulations, 2020, shall stand repealed from the date on which these regulations come into force.
Regulation 46(1)
Anything done under the 2020 Regulations, including registrations granted, is treated as done under the corresponding provisions of the 2026 Regulations (Regulation 46(2)).
Time to comply for existing portfolio managers: twelve months for the liquid-asset requirement (Regulation 4(a)(iv)(d)); thirty-six months to meet the commencement-of-business condition (Regulation 6(8)); and twelve months for existing client investments made before the 2020 Regulations to meet the minimum investment amount (Regulation 16(5)).
Until 31 March 2027, the 2020 Regulations still apply. Plan now: the twelve-month clocks start on 1 April 2027.
09
Section 9
Where to go next
All 46 regulations
The notified text, with plain-English notes.OpenKey numbers
Every threshold and time limit.OpenFAQs
Straight answers with their regulation.OpenQuiz
Test what you have learnt.OpenCalculators
Minimums, net worth, fees and dates.OpenTalk to CS Prashant Kumar
Apply the rules to your firm or clients.OpenThis guide explains the SEBI (Portfolio Managers) Regulations, 2026 as notified on 7 October 2026, in force from 1 April 2027. Quotes are from the notified text; explanations and examples are a learning aid, not legal advice. Circulars SEBI issues under these Regulations are not covered yet.
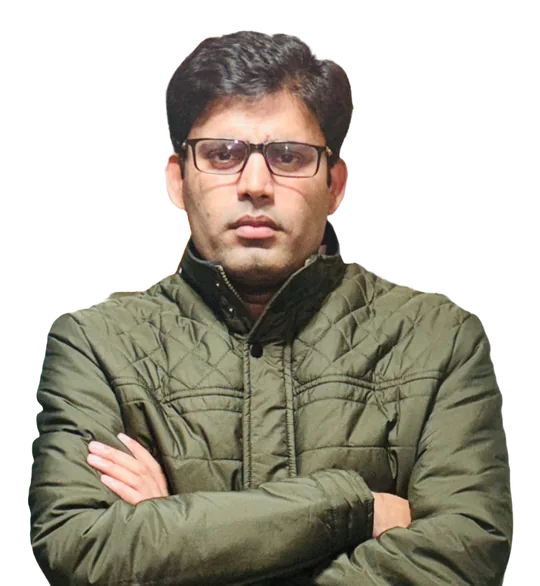
Meet the expert
CS Prashant Kumar
Company Secretary & Compliance Officer
Global Horizons Capital Advisors (IFSC) Private Limited — an IFSCA-licensed investment banker
Published in The Chartered Accountant (Jun 2025, Jan 2025, Mar 2024) and Chartered Secretary (Aug 2023)
Prashant Kumar is a seasoned Company Secretary and corporate governance strategist with more than 13 years of experience advising large corporates, promoter-led groups and global businesses on compliance, regulatory risk and board governance. In GIFT IFSC, the IFSCA regime is his day job rather than a research topic.